Buying another property can be an exciting financial milestone.
Some buyers want a vacation home where they can spend part of the year. Others want to purchase a property specifically to generate rental income. Although both involve purchasing an additional property, the mortgage classification can be different. Understanding the distinction is important before starting your application.
The short answer: a second home is for your personal use part of the year, while an investment property is not occupied by you and is often used to generate rental income. Each has separate underwriting, pricing and eligibility requirements. A licensed loan officer can help you compare mortgage loan options for either goal.
What is a second home?
A second home is a property that you intend to use personally for a portion of the year, rather than as your primary residence.
For eligible conventional financing, Fannie Mae guidelines describe requirements such as:
- The borrower uses the property as a second home for part of the year.
- The property is a one-unit dwelling.
- It is suitable for year-round occupancy.
- It remains under the borrower's exclusive control.
- It is not primarily operated as a rental property or timeshare arrangement.
Other requirements may apply.
What is an investment property?
An investment property is generally a property that the borrower does not occupy as a principal residence or qualifying second home.
Examples include:
- A house purchased for long-term rental.
- A residential property used to generate rental income.
- A property acquired primarily for investment purposes.
Investment properties have separate mortgage underwriting and pricing requirements. See our investment property loans page for more.
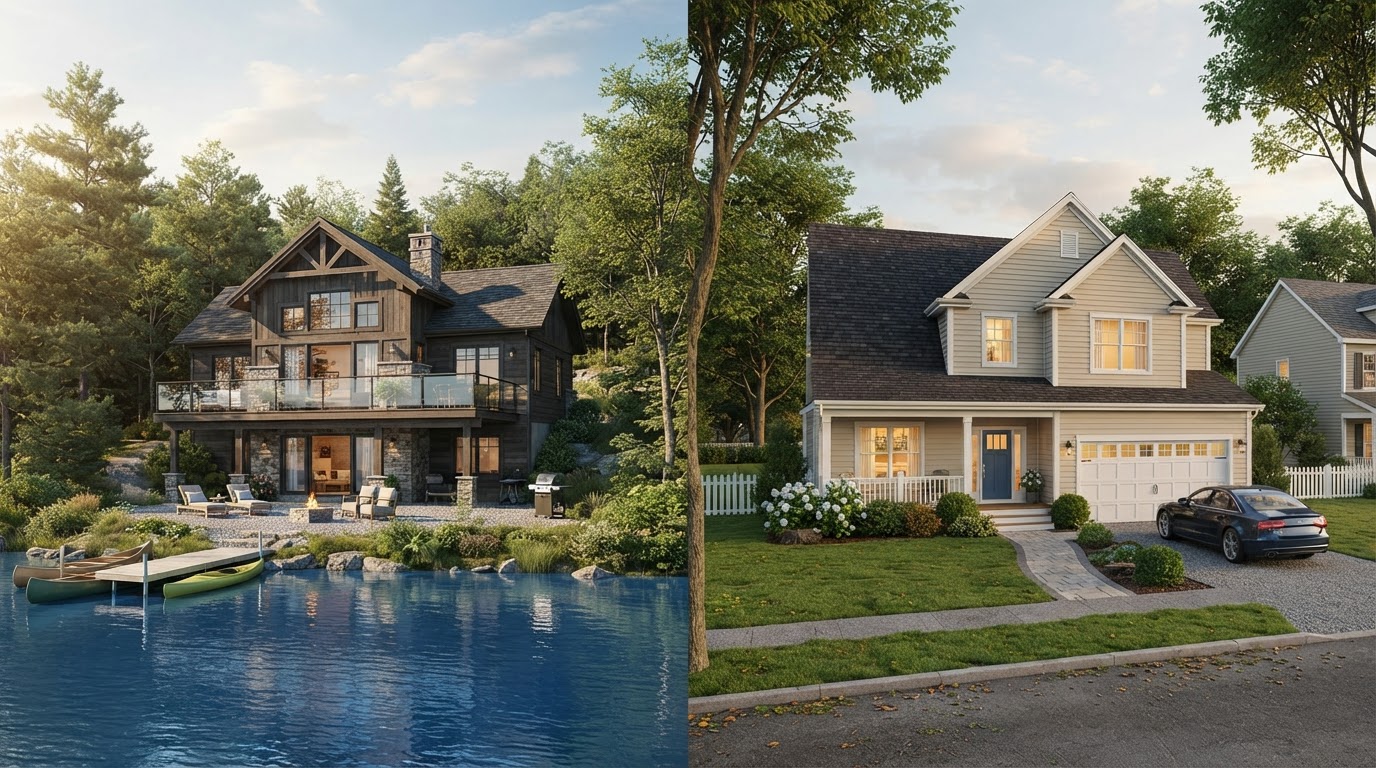
Second home vs. investment property
Second home
- Intended for personal use during part of the year.
- Must meet applicable second-home occupancy requirements.
- Has specific financing guidelines.
Investment property
- Not occupied by the borrower as a primary or qualifying second home.
- May be intended for rental income.
- Has different underwriting and pricing considerations.
How can the classification affect your mortgage?
Your property's intended use can influence:
- Available mortgage programs.
- Down payment requirements.
- Interest rate pricing.
- Cash reserve requirements.
- Income documentation.
- Property eligibility.
Requirements vary by lender and loan program.
Be honest about how you plan to use the property
One of the most important steps is accurately explaining your intended occupancy.
Do not classify an investment property as a second home simply to seek different financing terms. Misrepresenting occupancy can create serious mortgage and legal consequences. Discuss your actual plans with your lender before applying.
What should you consider before buying?
Evaluate:
- Your intended use.
- Available cash for the purchase.
- Property taxes.
- Insurance.
- Maintenance expenses.
- Rental income expectations, if applicable.
- Monthly payment affordability.
- Loan program requirements.
A property should make financial sense based on your personal circumstances. Use our mortgage calculator to estimate payments at different price points.
Frequently asked questions
Can I rent out my second home?
Certain rental arrangements may be allowed under specific second-home guidelines, but the property's primary purpose and occupancy requirements matter. Discuss your plans with the lender.
Is an investment property mortgage different from a regular mortgage?
Yes. Investment-property mortgages generally have separate eligibility, underwriting and pricing requirements.
Can I use rental income to qualify for a mortgage?
Some programs permit eligible rental income to be considered under specific documentation and calculation rules.
Does Vesta Lending offer investment property financing?
Investment property financing may be available depending on the company's current loan programs, licensing and eligibility requirements. Confirm with Vesta Lending.
Explore investment property financing with Vesta Lending
Whether you are considering a second home or an investment property, understanding your mortgage choices is important. Vesta Lending can help you explore financing options based on your goals. When you are ready, get a free quote or get pre-approved with Alex.
You can also call Alex Al-Ammar at (313) 992-9898 or email Alex@vestalending.com.
This article is for general information only. It is not legal, tax or financial advice. Loan programs, guidelines and eligibility depend on your credit, income, property and lender requirements. Occupancy rules vary by program and lender. Speak with a qualified professional about your individual situation.
Official reference: Fannie Mae Selling Guide — Occupancy Types