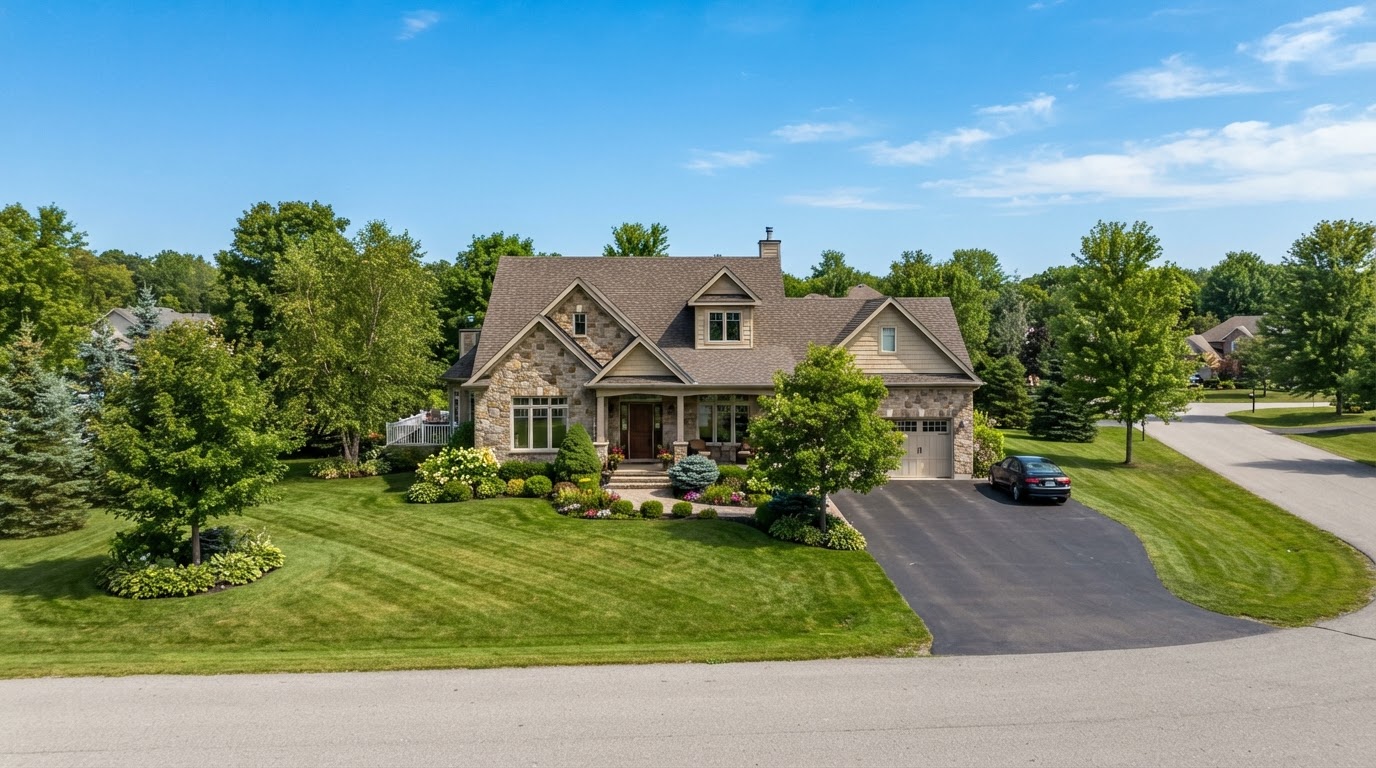
USDA home loans are designed to help eligible buyers purchase homes in qualifying rural and suburban areas. If you are shopping for a home outside a major city, a USDA loan may be worth exploring. Because the program's rules can change, always verify current USDA home loan requirements with a licensed loan officer.
The short answer: USDA loans may offer eligible buyers the possibility of no down payment on certain loans, but they have income limits, property eligibility rules and geographic restrictions. Learn more on our USDA loan page.
What is a USDA loan?
A USDA loan is a mortgage backed by the United States Department of Agriculture. The program is designed to support homeownership in eligible rural and suburban areas. Because the government guarantees the loan, lenders may offer terms that can help eligible buyers who have limited down payment savings.
Eligible locations
USDA loans are for homes in eligible rural and suburban areas. Eligibility is based on the property's location, not just whether the area "feels" rural. The USDA publishes maps and eligibility tools that show which areas qualify.
Many areas that buyers consider suburban actually qualify. It is worth checking a specific property address rather than assuming an area is not eligible.
Income limits
USDA loans have income limits based on the household and the area. The limits are designed to help moderate-income buyers. Income limits can vary by county and household size, and they are updated over time.
When you apply, the lender reviews your household income, which can include income from all adults in the household, not just the borrower. Confirm the current limits for your area with a loan officer.
Property requirements
The home must meet the USDA's property standards, which are designed to ensure the home is safe, sound and structurally sound. Requirements can include:
- The home must be in an eligible area
- The home must be your primary residence
- The home must meet minimum property standards
- The home must be modest in size and cost for the area
Investment properties and vacation homes are not eligible.
Occupancy requirements
USDA loans are for primary residences. You must intend to live in the home as your primary residence, generally within a reasonable time after closing.
Potential benefits of a USDA loan
For eligible buyers and properties, USDA loans may offer:
- The possibility of no down payment on certain loans
- Competitive rates, though rates vary by lender and market
- Flexible credit guidelines for eligible borrowers
Benefits depend on your eligibility, the loan and the lender. No loan is a guarantee, and USDA loans are subject to credit, income and property requirements.
How to check if you qualify
- Find a home in an eligible area using the USDA's eligibility tools.
- Check your household income against the area's limits.
- Talk with a lender that offers USDA loans.
- Get pre-approved to understand your price range.
- Confirm the property meets USDA standards.
Frequently asked questions
Can I use a USDA loan for a home in a city? USDA loans are for eligible rural and suburban areas. Some suburban areas qualify, so check the specific property address.
Do USDA loans require a down payment? Eligible buyers may be able to buy with no down payment on certain USDA loans, subject to the loan amount and the lender's requirements.
What are the income limits for a USDA loan? Income limits vary by area and household size and are updated over time. Confirm the current limits for your area with a loan officer.
Can I use a USDA loan for an investment property? No. USDA loans are for primary residences only.
Ready to see if a USDA loan fits?
When you are ready, get a free quote or get pre-approved with Alex.
You can also call Alex Al-Ammar at (313) 992-9898 or email Alex@vestalending.com.
This article is for general information only. It is not legal, tax or financial advice. USDA loan eligibility, income limits and property requirements change over time. Verify current guidelines with a qualified professional before making decisions.


